Why do seasonal businesses need a different kind of funding?
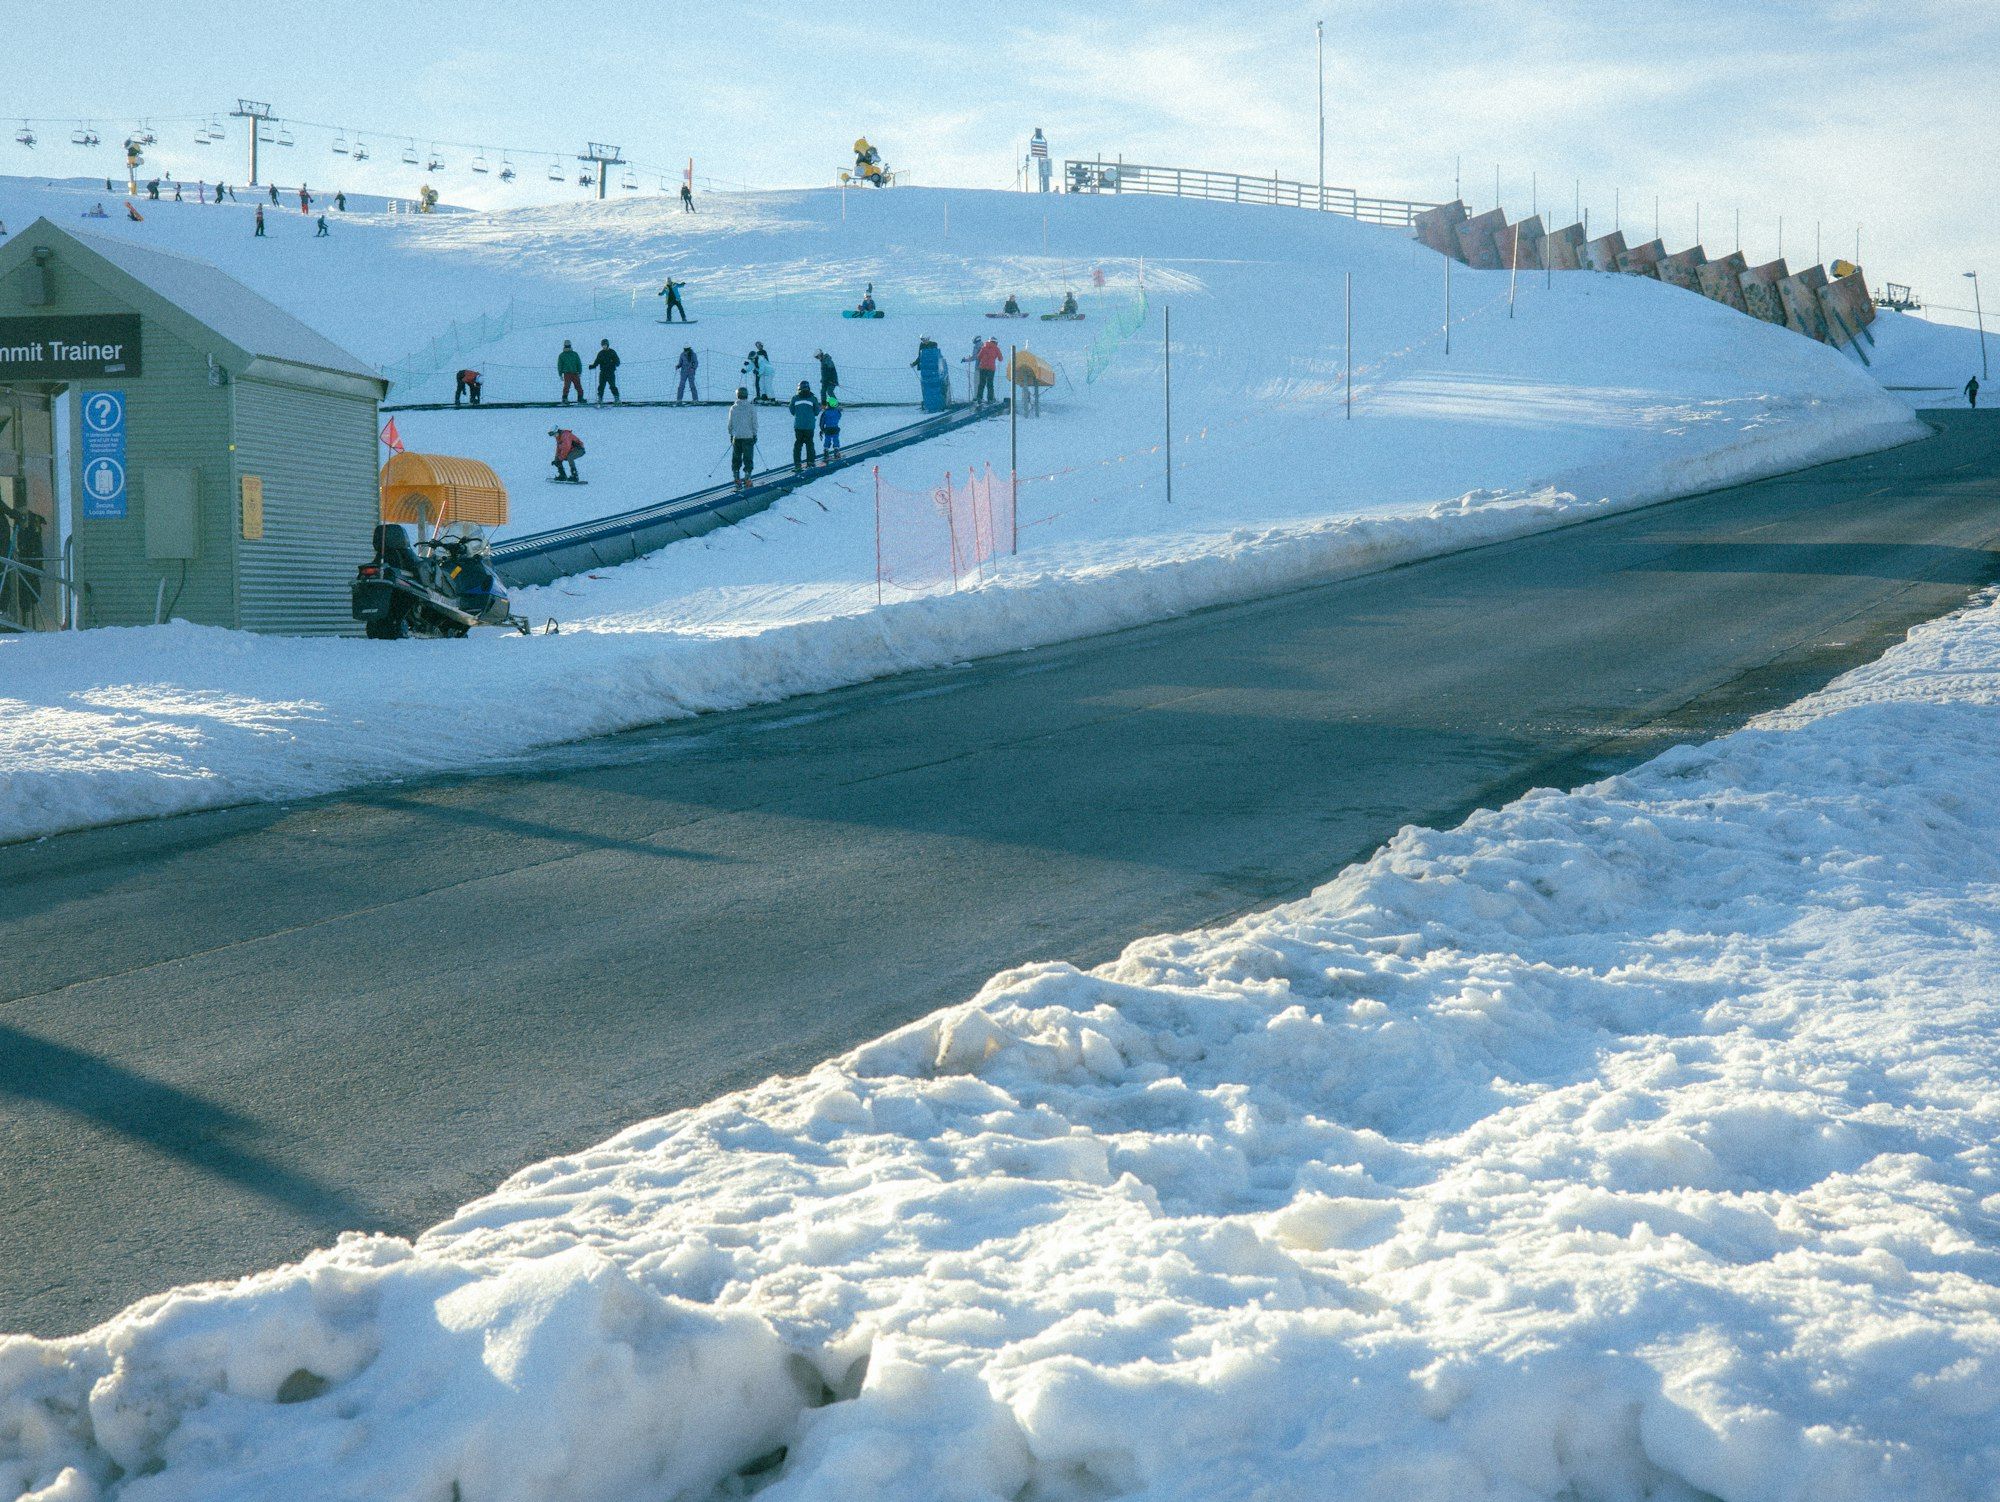
Most finance assumes a steady business: similar income every month, similar repayments every month. Australia’s seasonal economy doesn’t work like that. A lodge in the Snowy Mountains earns most of its year between the June long weekend and early October. A Barossa or McLaren Vale winery spends heavily through vintage, from late summer into autumn, and sells the wine much later. A reef operator in Port Douglas lives on the dry season. Tasmanian coastal accommodation fills over summer and thins out by winter.
Fixed monthly repayments bite hardest exactly when revenue is lowest. Seasonal funding reverses that: draw in the trough, repay in the peak.
What does the off-season actually cost?
Owners often underestimate it. The quiet months still carry:
- Rent and equipment leases, which don’t pause when bookings do.
- Core wages and super for the team you want back next season — and from 1 July 2026, Payday Super means super is due within seven business days of each payday.
- Maintenance and compliance — servicing boats and vehicles, recertifying lifts, renewing licences, repainting.
- Pre-season stock and inputs — fertiliser, packaging, winter hire gear or Christmas stock bought weeks before the first sale.
- Tax — a quarterly BAS or PAYG instalment that falls in a quiet quarter (see our guide to PAYG instalments for seasonal businesses).
Add these up across your longest quiet stretch and you have the rough size of the gap your funding needs to cover.
What do Australian seasons look like for cash flow?
| Business | Typical peak | Typical cash trough |
|---|---|---|
| Alpine lodges, ski hire, snow tours | June to early October | Late spring through autumn |
| Tropical north reef and tour operators | Dry season, roughly May to October | Wet season, roughly November to April |
| Wine grape growers and wineries | Vintage from late summer into autumn (spending) | Before grape payments and wine sales arrive |
| Queensland mango and NT growers | Late winter into summer harvest | Pre-harvest months carrying labour and packing costs |
| Coastal accommodation, Tasmania and the Gold Coast | Summer school holidays | Winter midweek |
| Retailers | Black Friday, Christmas, Boxing Day, EOFY sales | Stock-buying months before each peak |
Timing varies by region and year. Our Australian tourism seasonality data guide draws on Tourism Research Australia and ABS figures for a closer look.
Which funding structures fit a seasonal business?
- Business line of credit — draw in the trough, repay in the peak, reuse next year. Suits businesses usually trading six months or more with bank statement history.
- Unsecured working capital — a single lump sum for a specific gap, such as a pre-season stock order.
- Property-secured top-up — $20,000 to $1m secured on Australian property you or a supporting party own. Suits bigger one-off needs, such as a new tour vessel engine before the dry season or clearing an ATO balance left over from a poor year.
For most established seasonal businesses, the line of credit is the natural fit because it follows the shape of the year.
How do lenders read a seasonal business?
Twelve months of statements from a ski-season business will show four or five strong months and several lean ones. That’s fine when it’s explained. Lenders want to see that:
- The pattern repeats — this year’s peak looks broadly like last year’s.
- The peak clears the trough — in-season income is enough to repay what was drawn in the off-season.
- Costs flex — staffing and spending scale down sensibly when trade does.
Part of your lending specialist’s job is to present the business that way.
How might it work over a year?
Example scenario — illustrative only. A family-run lodge near Jindabyne arranges a line of credit in September, while winter takings are still flowing through its account. Over summer and autumn it draws to cover the manager’s wages, super, insurance, a roof repair and early marketing for the next season. Bookings and deposits start arriving in autumn, and the balance is cleared by August. The following year the same limit is waiting, with no new application.
How do you keep seasonal funding cheaper?
The less you draw and the sooner you repay, the less funding costs overall. A month-by-month seasonal cash flow plan is the most useful thing you can bring to a funding conversation: it shows the lender you know your year and shows you exactly how much capital to keep on call. Every facility is priced on your individual circumstances, so we don’t publish rates — we look for the sharpest option available for your situation.
What’s the next step?
The 60-second enquiry asks what your quiet months look like and what you need. It’s free and doesn’t affect your credit score, and a lending specialist will contact you to talk through the options.